Global Energy Crisis Surges as Iran Conflict Disrupts Oil Supply
A geopolitical choke point has forced a debate about whether energy security is solved by markets, institutions, or strategic government action.
The brief
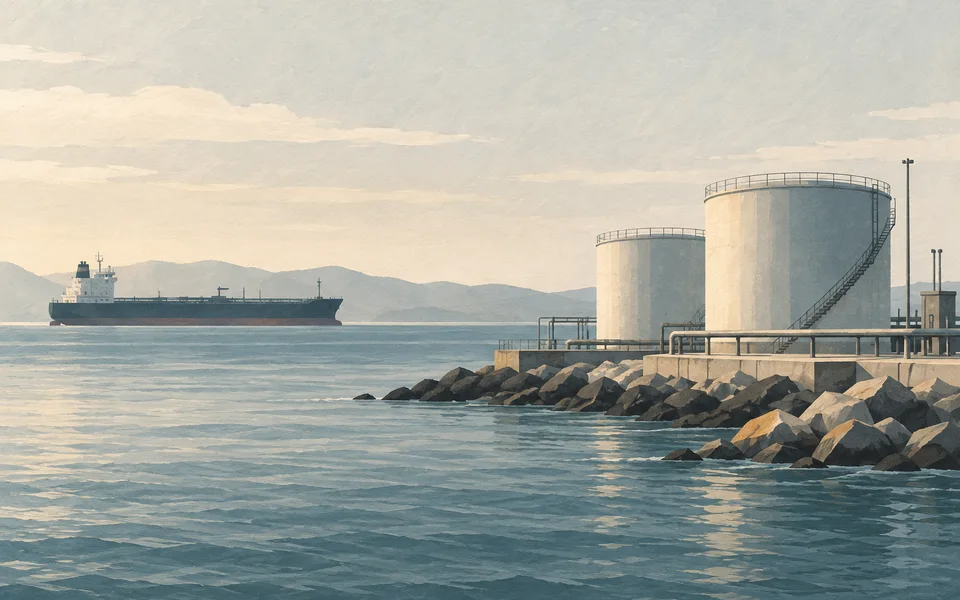
A rapid shutdown and disruption of traffic through the Strait of Hormuz after military strikes and retaliatory attacks has removed roughly one-fifth of global oil flows and large volumes of LNG from world markets. Governments, international agencies, and markets disagree on the interpretation and remedy: some actors treat the crisis as an unprecedented supply shock that requires centralized, institution-led coordination (strategic reserves, sanctions enforcement, diplomatic containment and new chokepoint protections), while others emphasize market signals and supply-side diversification (alternative shipping routes, increased production outside the Gulf, and accelerated investment in domestic energy). Underneath these disagreements are deeper conflicts about which institutions are credible, how much short-term intervention is legitimate, and whether long-term energy transformation should be accelerated as a strategic imperative or subordinated to immediate supply relief.
In late February–March 2026 the Iran conflict escalated into attacks and counterattacks that effectively shut or heavily disrupted the Strait of Hormuz, the maritime chokepoint through which an outsized share of Gulf oil and LNG transits. Multiple reporting and institutional estimates converge around an immediate and massive shock: roughly 20% of global oil supply was disrupted, and analysts estimate losses on the order of 11 million barrels per day of oil and oil products plus around 300 million cubic meters per day of LNG within one month of the outbreak.
Those raw numbers explain why price signals were so dramatic: Brent and other benchmarks jumped above US$100 per barrel in early March, reflecting both the immediate physical shortage and the fear of prolonged interruption. The International Energy Agency (IEA) called the situation the "greatest global energy security threat in history," comparing the scale of production losses and chokepoint disruption unfavorably even with the 1973 embargo and the supply impacts since the Ukraine war. Financial institutions and research groups reached similar conclusions about the size and uniqueness of the shock.
Responses diverged quickly along institutional and ideological lines. Some governments — and multilateral actors — pushed coordinated steps: releases from strategic petroleum reserves, diplomatic pressure to reopen transit corridors, protection of merchant shipping, and contingency planning to reroute trade. The EU warned that prices and flows would not immediately normalize even if hostilities paused, while the IEA sounded repeated alarms about structural vulnerability.
Other actors emphasized market-driven adjustments: higher prices, they argued, would incentivize non-Gulf production, prompt re-routing of tankers around Africa where possible, and accelerate incremental LNG shipments from alternative suppliers. Private-sector analysis from banks and oil-market analysts underscored the role of inventory management, hedging, and longer-term contracts in stabilizing flows.
A parallel debate quickly became political: some countries — particularly import-dependent, lower-income states in Asia and the Middle East — introduced domestic measures such as price caps, subsidy adjustments, and rationing to blunt immediate consumer pain. This produced secondary effects: rising inflation, currency pressure in vulnerable economies, and heightened food-security risk due to higher fertilizer and transport costs.
Beyond near-term remedies, the crisis sharpened a broader policy fault line. One side argues that the episode reveals the fragility of an energy system still dependent on volatile geopolitical chokepoints and therefore validates rapid acceleration of diversification and renewables, together with strong international institutions to coordinate emergency response. The other side warns that overreliance on institutions and top-down rationing risks inefficiency and that market mechanisms and supply-side increases (including reactivated production outside the Gulf) are the fastest route to restoring energy security.
Crucially, this disagreement is not only about technical trade-offs (how to fill barrels in the short term) but about which institutions and signals are credible. Where the IEA and allied governments call for coordinated mitigation and warn of long-term insecurity, skeptics highlight the power of price signals, private investment, and unilateral national measures to secure supplies. Trust in international agencies, in governmental competence to manage markets, and in the impartiality of oil-producing states shapes which remedies each actor finds legitimate.
Messaging and messenger credibility have amplified disagreement. Countries asking for coordinated relief sometimes distrust major producers’ willingness to expand exports; some producing states question whether releasing strategic reserves undermines market discipline. Public opinion in importers is shaped by immediate fuel shortages and inflation, which can increase political pressure for short-run relief measures even when economists warn of long-run market distortions.
The practical consequences are stark: supply interruptions of this scale create winners and losers quickly — from shippers and traders to vulnerable importers and agricultural consumers — while political responses (price controls, rationing, reserve releases) have blowback that can entrench divisions about how to handle future crises. The episode therefore becomes a test of institutional credibility as much as a test of pipelines and tankers. Whether the world moves toward deeper cooperation, rapid market rebalancing, or a politicized scramble will depend as much on which actors gain trust in the coming weeks as on the physical restoration of Gulf flows.
Key facts
11 pointsCheck the reporting behind each point.
About 20% of global oil supply has been disrupted due to the closure of the Strait of Hormuz and related shipping interruptions caused by the Iran conflict.
Approximately 11 million barrels per day (bpd) of crude oil and oil product supply, plus around 300 million cubic meters of LNG per day, were lost in the month following the conflict's outbreak—more than 10% of global oil consumption.
Oil prices surged past US$100 per barrel (Brent) in early March, driven by fears of prolonged disruption even where immediate regional supply remained adequate.
Sources for this story 21 links
Links show the reporting used for this brief. Multiple links may report the same underlying account; they do not automatically mean independent confirmation.
Compare perspectives
See what each framing puts first, leaves out, and worries about.
What matters most in each reading?
Institutional coordination and fair protections
Progressive-leaning framing
- Immediate humanitarian and macroeconomic impact
- Role of international institutions and coordinated action
- Acceleration of green transition as strategic resilience
Resilience through markets and national measures
Conservative-leaning framing
- Market signals and energy independence
- Rapid diversification of supply and national resilience
- Skepticism of over-centralized, slow institutional fixes
Illustrative editorial analysis, not a survey of news coverage. These readings do not represent everyone or imply that both arguments have equal evidence.
Practice a conversation about this story
More from Economy.